
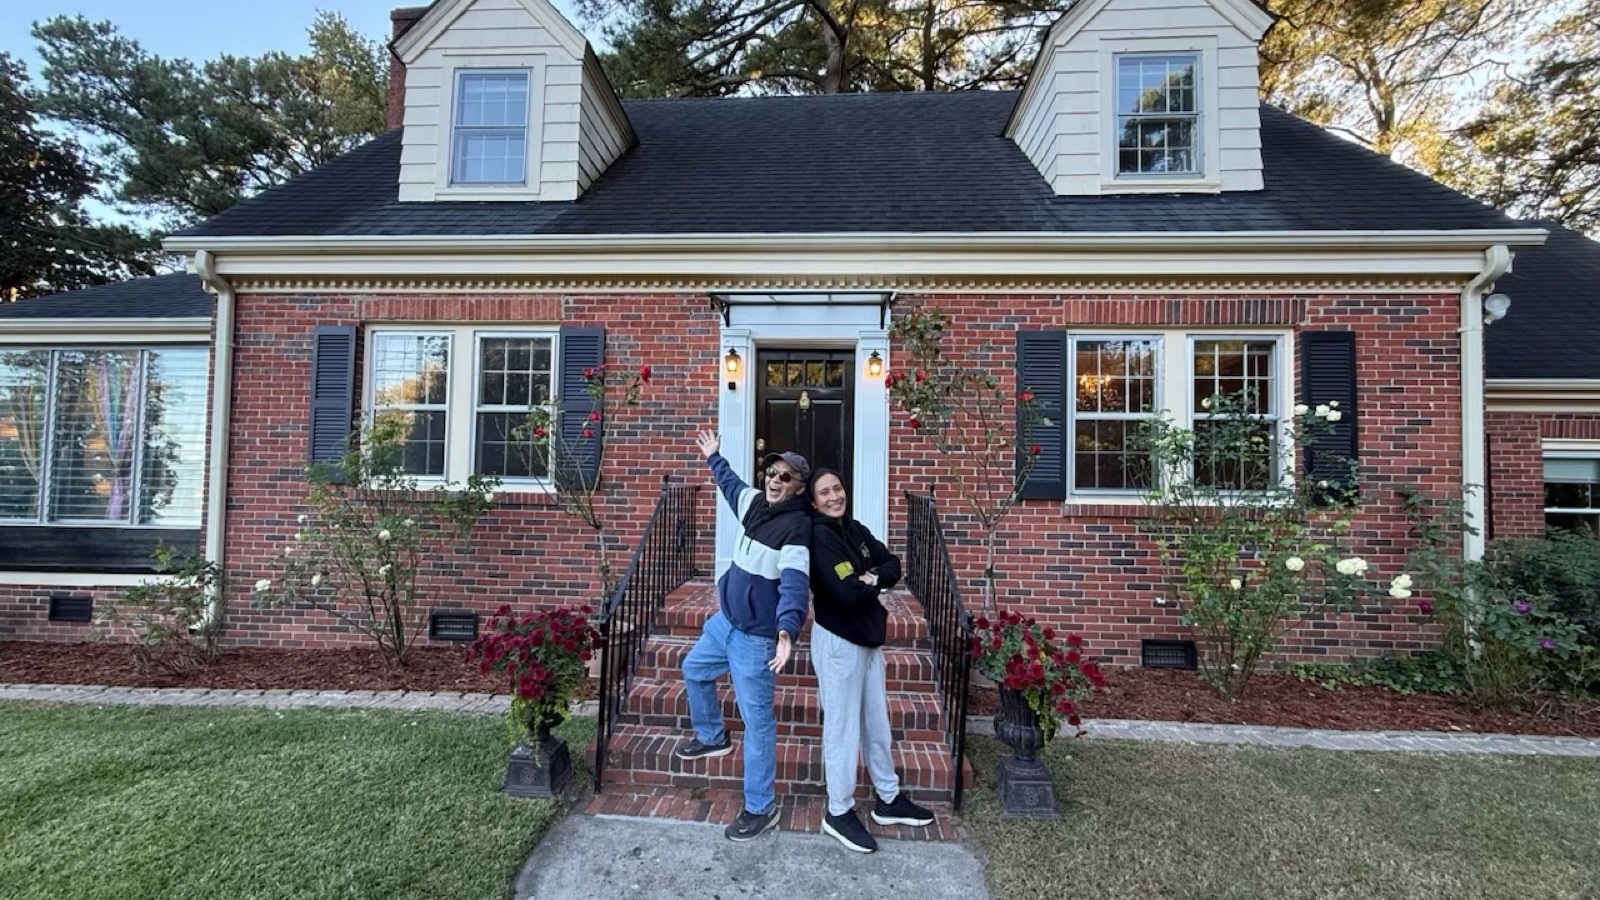
This closing meant a lot to me. My clients are veterans, buying for the second time, and when we first talked they believed what most people believe: that to buy the next house, you sell the one you are in. They also had a reason to move that had nothing to do with square footage. Their daughter lives down the street from this house, and she is expecting their first grandchild.
What they did not know is that a VA home loan benefit does not get used up by one purchase. They could keep their current home, move out and rent it, and still buy this one with their VA benefits, using what is called bonus entitlement. Because they had enough entitlement left, the down payment on this home was small.
“They had no idea that they could keep their current property, vacate it as a rental, and still purchase utilizing their VA benefits.”
This closing, in brief
- Who
- A veteran couple, buying for the second time
- Where
- Down the street from their daughter, Inland Empire
- Loan
- VA purchase using remaining (bonus) entitlement
- First home
- Kept, and converted to a rental
- Down payment
- A small share of the price
- Why it mattered
- Their first grandchild is on the way
What "entitlement" means
The VA does not lend the money. It guarantees part of the loan, which is why VA loans are known for low up-front costs and no monthly mortgage insurance. That guarantee is your entitlement. When you buy a home with a VA loan, part of it is tied up in that loan. The part that is left is your remaining, or bonus, entitlement, and it can be used to buy another home while you still own the first one.
How much you have left depends on the size of your current VA loan and the loan limit for the county you are buying in. Those two things decide whether you need a down payment on the new home, and how much. Here, it was far smaller than they expected.
You must live in the new home. You do not have to sell the old one.
The first home can become a rental, and in many cases the rent can even help you qualify for the new loan. We walk through the occupancy rules, the county loan limit and the entitlement math before anyone falls in love with a house, so the answer is known on day one and not on day twenty.
Three numbers I ask for on day one
I worked my way up to underwriter, so I read a file the way an underwriter will. On a second-time VA purchase, three things early tell us what the down payment will be, if there is one. Our team prepares each step, and I review the files that may be a bit more difficult, so there are no surprises.
- 1Certificate of EligibilityShows the entitlement already in use on the first home, and what remains.
- 2The first home's numbersIts current mortgage, and what it will rent for once you move.
- 3The county loan limitSets how far the remaining entitlement stretches on the new home.
Questions veterans ask us
Can I use my VA benefit more than once?
Yes. Entitlement is restored when a VA loan is paid off, and remaining entitlement can be used while you still own the first home.
Do I have to sell my current home to buy with VA again?
No. You can keep it and rent it out. You must intend to live in the new home as your primary residence.
Will I need a down payment on the second VA loan?
It depends on your remaining entitlement and the county loan limit. We work out whether you need one, and how much, before you look at homes.
Does the rent from my first home count as income?
Often, with documentation and a reserve requirement. We check it before you make an offer.
Is there mortgage insurance on a VA loan?
No monthly mortgage insurance. There is a one-time VA funding fee, which some veterans are exempt from.
“This family is so excited to move right down the street from their daughter, who is having their first grandchild.”
The Brandon Drew Group, a division of New American Funding, LLC, NMLS #6606 (www.nmlsconsumeraccess.org). Branch NMLS #2882133. Colleen Olivas NMLS #379721. Equal Housing Lender. VA loans are subject to VA eligibility, entitlement, occupancy and underwriting requirements; terms and any down payment depend on remaining entitlement and county loan limits. This is not a commitment to lend. Clients' names and details withheld; story shared with permission.